
C
Robinhood Chain sees $10B in stock token trading volume, up 672%
Robinhood Chain's rapid growth highlights the potential for tokenized equity markets, but reliance on few traders poses sustainability risks.
 CryptoBriefing•Editorial Team6h ago
Robinhood Chain's rapid growth highlights the potential for tokenized equity markets, but reliance on few traders poses sustainability risks.
CryptoBriefing•Editorial Team6h ago
Robinhood's disclaimer highlights the risks of speculative trading on its chain, emphasizing user responsibility and potential market volatility.
CryptoBriefing•Editorial Team7h ago
Solana just took the most historic step in its governance history: its first real on-chain vote, where any SOL holder — not just validators — could weigh in on the network's constitution, inflation and fees. Camila Russo sits down with Nick Almond, Head of Governance at the Jito Foundation, right
 The Defiant•Camila Russo8h ago
The launch of Overcall on Robinhood Chain could enhance decentralized trading, potentially reshaping market dynamics and user engagement.
CryptoBriefing•Editorial Team12h ago
Robinhood CEO declares ‘Tokenization is coming to America’ after historic SEC rules greenlight 24/7 blockchain stock trading.
 U.Today•Gamza Khanzadaev12h ago
The launch enhances Robinhood Chain's DeFi ecosystem, potentially increasing stablecoin liquidity and competition among decentralized exchanges.
CryptoBriefing•Editorial Team13h ago
The looming end of Robinhood's gas subsidy may shift focus from speculative meme tokens to sustainable, real-world asset tokenization.
CryptoBriefing•Editorial Team16h ago
HTX Research, the dedicated research arm of HTX, has released a new report titled Stock-Linked Memecoins: Issuance, Liquidity, and the Emerging AMM Stack, a systematic study of a new asset category that emerged following the launch of Robinhood Chain. These memecoins are paired directly with stock tokens representing names such as NVDA, TSLA, HIMS, and
 BeInCrypto•Advertorial18h ago

Apia, Samoa, September 17 – HTX Research, the dedicated research arm of HTX, has released a new report titled Stock-Linked Memecoins: Issuance, Liquidity, and the Emerging AMM Stack, a systematic study of a new asset category that emerged following the launch of Robinhood Chain. These memecoins are paired directly with stock tokens representing names such as NVDA, TSLA, HIMS, and MU, using them as quote asset, narrative anchor, or liquidity base. The report finds that they combine public-equity price discovery, crypto attention, AMM inventory, and continuously traded sentiment into a single market structure — the short-term growth case holds, but durability depends on four conditions being met simultaneously. A New Market Structure A stock-linked memecoin is a second-order equity exposure. The stock token provides a first-order price anchor, while the memecoin trades the culture, events, and sentiment surrounding that stock, often with volatility far exceeding the underlying. It resembles an attention derivative on an equity theme rather than a legally structured equity derivative. Robinhood Chain is unusually well suited to this experiment. Robinhood brings a recognized retail-equity brand and stock tokens carrying familiar company symbols rather than an abstract RWA narrative; Uniswap became a major liquidity venue from launch; and O1 Launchpad productized the process of selecting a stock token, creating a memecoin, opening a Uniswap v4 market, and allocating trading fees. As of September 8, 2026, DeFiLlama reported approximately $901 million in Robinhood Chain TVL and $1.727 billion in 24-hour DEX volume. Multi-Hop Routing and Toll Collectors on Attention Value capture extends beyond the memecoin itself. A trader buying a stock-linked memecoin may travel from WETH to USDG to a stock token and finally to the memecoin, with a single order generating fees for several pools along the way. During a short-lived attention spike, volume rises sharply while liquidity remains thin, and liquidity providers become the ecosystem’s most direct toll collectors on attention. High fees, however, do not imply high net returns. Risks including out-of-range positions, one-sided inventory, impermanent loss, stock-market closures, stock-token premiums or discounts, and incentive-token depreciation can all outweigh headline fee income. As HTX Research emphasizes, fees are compensation for risk, not free interest — LPs bear the risk of continuously filling at the wrong price, while traders bear the risk of picking the wrong token. The 100,000% APY Illusion Market commentary has cited displayed APY above 100,000% for supplying high-fee Uniswap v4 liquidity to stock-linked memecoins. The report dismantles this figure, noting that a short observation window, sudden volume surge, small TVL base, and compound extrapolation are all it takes to display an extreme annualized rate. If a $100,000 position earns $200 in one hour, simple annualization produces approximately 1,752%, and hourly compounding turns it into an astronomical number. Annualized metrics also ignore denominator effects — when a memecoin collapses, dividing unchanged fees by a smaller ending TVL inflates the displayed yield. The report proposes a more robust test: the fee-coverage multiple – realized fees and monetized incentives divided by losses relative to a simple hold portfolio, rebalancing costs, and hedging costs. Only a multiple above one indicates that market making has compensated for its risk. High APY still carries information value as a signal of dense order flow relative to effective depth, and professional LPs can treat it as a flow radar rather than a return promise. Four Conditions and the Real Questions HTX Research identifies four questions that will determine whether stock-linked memecoins evolve from an onchain experiment into a durable market structure: Are Robinhood’s native users actually moving onchain? Do stock-token redemption and pricing remain stable during extreme moves and market closures? Does issuance from O1 and comparable platforms turn into markets with two-sided depth after seven and thirty days? Can AMMs preserve effective depth and organic volume as subsidies fall? If the answer to each is yes, stock-linked memecoins can become a high-volatility front end for the internetization of equities, with issuance platforms and AMMs forming a new market stack. If not, the current heat is more likely a temporary experiment driven by low float, heavy subsidies, cheap issuance, and transient attention. Either way, 100,000% APY should never be the endpoint of research. As HTX Research points out, the relevant questions are who pays the fee, who carries the inventory, who can exit, who controls protocol parameters, and whether revenue survives after incentives stop. This reflects HTX Research’s consistent approach to emerging market forms — dissecting structure, fee attribution, and risk sources before drawing conclusions from headline figures. HTX Research will continue tracking issuance, liquidity, and user-composition shifts across Robinhood Chain and comparable ecosystems, providing structural analysis grounded in onchain data. About HTX Research HTX Research is the dedicated research arm of HTX Group, responsible for conducting in-depth analyses, producing comprehensive reports, and delivering expert evaluations across a broad spectrum of topics, including cryptocurrency, blockchain technology, and emerging market trends. Committed to providing data-driven insights and strategic foresight, HTX Research plays a pivotal role in shaping industry perspectives and supporting informed decision-making within the digital asset space. Through rigorous research methodologies and cutting-edge analytics, HTX Research remains at the forefront of innovation, driving thought leadership and fostering a deeper understanding of evolving market dynamics. Visit us. Connect with HTX Research Team: research@htx-inc.com
 NewsBTC•BlockmanPR19h ago
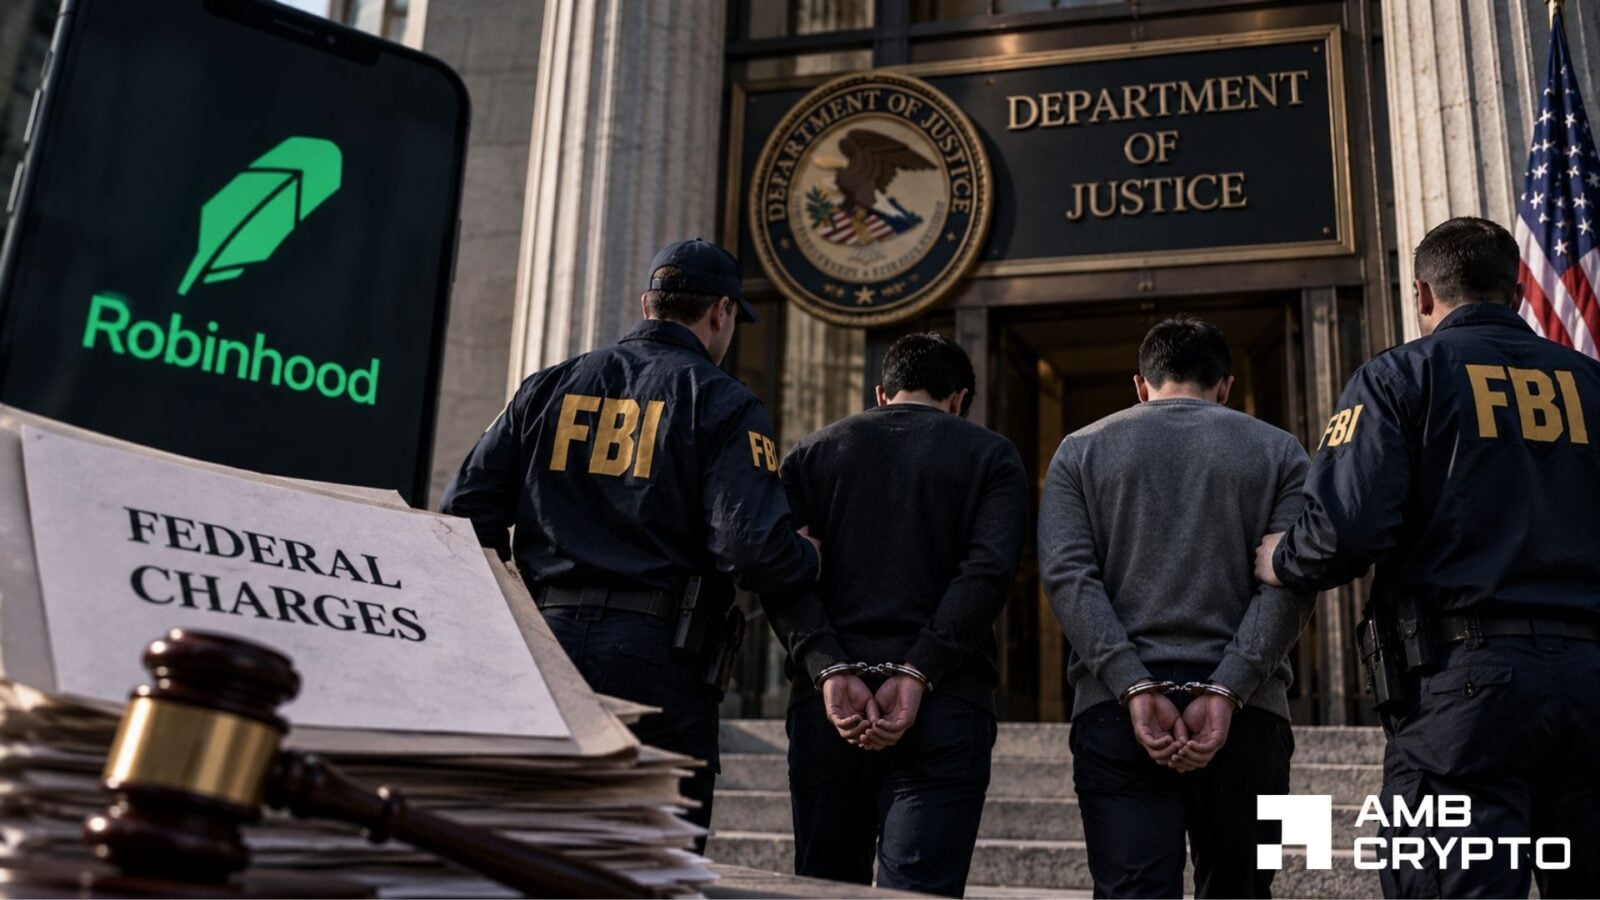
Charges against Robinhood engineers marks a new wave of DoJ crackdown against crypto insider trading
 AMBCrypto•Benjamin Njiri17 Sept
Two Robinhood engineers allegedly used confidential crypto listings to insider trade on decentralized derivatives exchange Hyperliquid.
 Protos•Jacob Lyon16 Sept
The chain's one-month TVL growth stands at 71%, yet net outflows of $11.11 million over 24 hours show capital can still move quickly.
DOJ says confidential token-listing plans fueled perpetual-futures trades ahead of Robinhood announcements.
 CryptoSlate•Oluwapelumi Adejumo16 Sept
Crypto insider trading charges allege two former Robinhood engineers used Hyperliquid perpetual futures before token listings, prosecutors say.
 CoinDesk•Olivier Acuna16 Sept

Federal prosecutors have charged two former Robinhood engineers with commodities fraud and wire fraud for allegedly trading perpetual futures on Hyperliquid using confidential information about upcoming cryptocurrency listings, with each profiting more than $50,000.
 The Daily Hodl•Daily Hodl Agent16 Sept
Federal prosecutors in Manhattan unsealed complaints Tuesday charging two Robinhood engineers, Hefu Chai and Huaisong Xiang, also known as Jerry Xiang, with commodities fraud and wire fraud. The charges stem from an alleged scheme to misappropriate confidential business information from Robinhood Markets. This is used to trade perpetual futures on
 TheNewsCrypto•Sarayu Krishna16 Sept
The former employees allegedly earned more than $50,000 each by trading Hyperliquid perpetuals ahead of Robinhood token listings.
 Cointelegraph•Cointelegraph by Ezra Reguerra16 Sept
Robinhood shares dropped more sharply than the wider US market, leaving HOOD near an important short-term price level.
AMBCrypto•Adewale Olarinde15 Sept
Federal prosecutors have charged two Robinhood engineers with commodities fraud and wire fraud after each allegedly earned more than $50,000 by trading crypto perpetual futures with confidential listing information. Robinhood engineers allegedly traded before listings The U.S. Attorney’s Office for…